Navigating the 2026 Retirement Account Contribution Limits: Your Essential Guide to Roth and Traditional IRA Updates
As we look towards the future of financial planning, understanding the evolving landscape of retirement accounts is paramount. The year 2026 brings with it new adjustments to the 2026 IRA Limits for both Roth and Traditional Individual Retirement Accounts. These changes, while sometimes subtle, can have a significant impact on your long-term savings strategy and your ability to achieve a comfortable retirement. For anyone serious about their financial future, staying informed about these updates is not just beneficial, it’s essential.
Retirement planning is a dynamic process, influenced by inflation, economic conditions, and legislative adjustments. The IRS periodically revises contribution limits to reflect these factors, aiming to help individuals save more effectively while also considering the broader economic environment. This comprehensive guide will delve into the specifics of the 2026 IRA Limits, providing you with a clear understanding of what to expect, who is affected, and how you can best leverage these changes to your advantage. Whether you’re a seasoned investor or just beginning your retirement savings journey, this information will empower you to make informed decisions and optimize your contributions.
We’ll explore the updated contribution ceilings, discuss the income phase-out ranges for Roth IRAs, and examine the deductibility rules for Traditional IRAs. Furthermore, we’ll offer practical strategies to maximize your savings within these new limits, including insights into catch-up contributions for those aged 50 and over. Our goal is to equip you with the knowledge needed to confidently navigate the 2026 IRA Limits and build a robust financial foundation for your golden years.
Understanding the Fundamentals: Roth vs. Traditional IRA
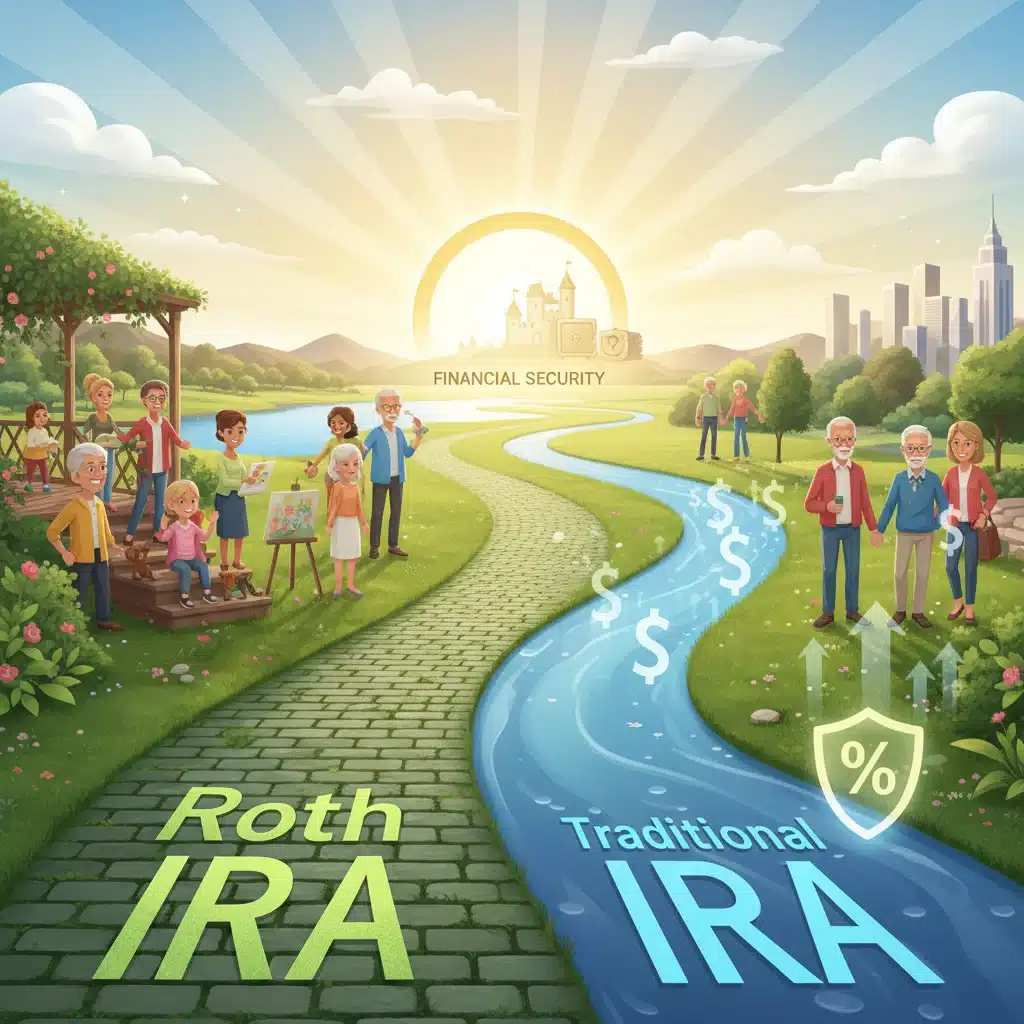
Before diving into the specifics of the 2026 IRA Limits, it’s crucial to have a solid understanding of the fundamental differences between Roth and Traditional IRAs. Each account type offers unique tax advantages, and the best choice for you often depends on your current income, anticipated future income, and overall financial goals.
Traditional IRA: Tax-Deductible Contributions, Taxable Withdrawals
A Traditional IRA allows you to contribute pre-tax dollars, meaning your contributions might be tax-deductible in the year they are made. This can lead to an immediate tax break, reducing your taxable income. The money within a Traditional IRA grows tax-deferred, meaning you don’t pay taxes on investment gains until you withdraw the funds in retirement. When you do take withdrawals in retirement, they are taxed as ordinary income. This structure is often advantageous for individuals who expect to be in a lower tax bracket in retirement than they are during their working years.
Roth IRA: After-Tax Contributions, Tax-Free Withdrawals
In contrast, a Roth IRA is funded with after-tax dollars. Your contributions are not tax-deductible, so there’s no upfront tax break. However, the significant advantage of a Roth IRA comes in retirement: qualified withdrawals are completely tax-free. This includes both your original contributions and all the investment earnings. A Roth IRA is particularly appealing for those who anticipate being in a higher tax bracket in retirement or who value the certainty of tax-free income in their later years. It also offers more flexibility with withdrawals, as contributions can be withdrawn tax-free and penalty-free at any time.
Understanding these core differences is the first step in deciding which type of IRA, or combination of both, best suits your financial strategy, especially when considering the new 2026 IRA Limits. Your personal circumstances, including your current income, your projected income in retirement, and your overall tax strategy, will play a significant role in determining the most beneficial approach.
The Anticipated 2026 IRA Contribution Limits
While the official numbers for the 2026 IRA Limits are typically announced by the IRS in the fall of the preceding year, we can make informed projections based on historical trends, inflation rates, and economic forecasts. The IRS adjusts these limits annually to keep pace with the cost of living, as measured by the Consumer Price Index for All Urban Consumers (CPI-U). These adjustments are designed to ensure that the purchasing power of your retirement savings is maintained over time.
For 2026, it is highly probable that we will see an increase in the standard IRA contribution limit for both Traditional and Roth accounts. While specific figures are speculative until official release, past adjustments suggest a potential increase of $500 to $1,000 from the previous year’s limits. This means the standard contribution limit, which was $7,000 in 2024, could rise to approximately $7,500 or even $8,000 for 2026. It’s crucial to monitor official IRS announcements as they become available to confirm these figures.
Catch-Up Contributions for Those Aged 50 and Over
An important aspect of the 2026 IRA Limits, particularly for those nearing retirement, are catch-up contributions. Individuals aged 50 and older are permitted to contribute an additional amount above the standard limit. This provision is designed to help older workers boost their retirement savings if they started late or simply want to accelerate their contributions. The catch-up contribution limit also tends to be adjusted periodically. For 2024, it was $1,000, bringing the total possible contribution for those 50 and over to $8,000. For 2026, we might see this catch-up limit remain stable or experience a slight increase, potentially pushing the total contribution for this demographic even higher.
These increased limits provide a valuable opportunity to accelerate your retirement savings. Whether you’re contributing to a Traditional or Roth IRA, understanding these potential increases allows for proactive financial planning. It’s a good practice to review your contribution strategy annually and adjust it to meet the new 2026 IRA Limits as soon as they are confirmed.
Roth IRA Income Limits and Phase-Out Ranges for 2026
Unlike Traditional IRAs, Roth IRAs come with income limitations that determine who can contribute directly to them. These Modified Adjusted Gross Income (MAGI) limits are also subject to annual adjustments by the IRS, and we anticipate changes for the 2026 IRA Limits. The income phase-out ranges mean that as your income rises above a certain threshold, the amount you can contribute to a Roth IRA begins to decrease, eventually phasing out entirely.
For 2026, the MAGI phase-out ranges for Roth IRA contributions are expected to increase, reflecting inflation and economic growth. For single filers and heads of household, the lower end of the phase-out range could potentially start around $160,000 to $165,000, with the upper end reaching approximately $175,000 to $180,000. For married couples filing jointly and qualifying widow(er)s, these ranges could begin around $240,000 to $245,000, phasing out completely around $255,000 to $260,000. These are projections, and actual figures will be released by the IRS.
If your MAGI falls within the phase-out range, you can only contribute a reduced amount to a Roth IRA. If your MAGI exceeds the upper limit of the phase-out range, you are generally not eligible to make direct Roth IRA contributions. However, this doesn’t necessarily mean you can’t have a Roth IRA. The “backdoor Roth IRA” strategy remains a popular option for high-income earners. This involves contributing to a Traditional IRA (which has no income limits for contributions, though deductibility may be limited) and then converting it to a Roth IRA. This strategy allows individuals to bypass the direct income limitations, though it requires careful consideration of tax implications, especially if you have existing pre-tax IRA balances.
Understanding these evolving income thresholds is critical when planning your contributions to align with the 2026 IRA Limits, particularly if your income is close to or exceeds these projected ranges. Consulting with a financial advisor can help you navigate these complexities and determine the most tax-efficient way to contribute to your retirement savings.
Traditional IRA Deductibility Rules for 2026
While there are no income limits for contributing to a Traditional IRA, the deductibility of your contributions can be affected by your income and whether you or your spouse are covered by a retirement plan at work (such as a 401(k), 403(b), or pension plan). These deductibility rules are also subject to annual adjustments, and we anticipate new thresholds for the 2026 IRA Limits.
If You Are Covered by a Workplace Retirement Plan
If you are covered by a retirement plan at work, the deductibility of your Traditional IRA contributions will depend on your Modified Adjusted Gross Income (MAGI). For 2026, the phase-out ranges for deductibility are expected to increase. For single filers, the MAGI phase-out could begin around $78,000 to $83,000, fully phasing out around $88,000 to $93,000. For married couples filing jointly, where the IRA contributor is covered by a workplace plan, the phase-out could start around $129,000 to $134,000, fully phasing out around $149,000 to $154,000. If you fall within these ranges, your deduction will be reduced. If your MAGI exceeds the upper limit, your contribution will not be deductible.
If You Are NOT Covered by a Workplace Retirement Plan
If neither you nor your spouse is covered by a retirement plan at work, your Traditional IRA contributions are fully deductible, regardless of your income. This provides a significant tax benefit, allowing you to reduce your taxable income by the full amount of your contribution, up to the 2026 IRA Limits.
If Your Spouse Is Covered by a Workplace Retirement Plan (But You Are Not)
There’s a special rule for married couples filing jointly where one spouse is covered by a workplace retirement plan and the other is not. In this scenario, the spouse who is not covered by a workplace plan can deduct their Traditional IRA contributions, but this deductibility is subject to a much higher MAGI phase-out range. For 2026, this range could begin around $240,000 to $245,000, fully phasing out around $250,000 to $255,000. This rule allows higher-income couples to still receive a deduction for at least one spouse’s IRA contributions.
Understanding these deductibility rules is crucial for maximizing the tax benefits of your Traditional IRA contributions within the framework of the 2026 IRA Limits. If your contributions are not deductible, you are essentially contributing after-tax dollars, and you might consider whether a Roth IRA or a non-deductible Traditional IRA (potentially for a backdoor Roth conversion) is a more appropriate strategy.
Strategies to Maximize Your Savings Under the 2026 IRA Limits
With the anticipated adjustments to the 2026 IRA Limits, now is an opportune time to review and refine your retirement savings strategy. Maximizing your contributions can significantly impact your financial security in retirement. Here are several strategies to consider:
1. Max Out Your Contributions Early
One of the most effective strategies is to contribute the maximum allowable amount to your IRA as early in the year as possible. This allows your money more time to grow through compounding, potentially leading to substantially larger balances over the long term. Even if you can’t contribute the full amount at once, setting up automatic monthly contributions can help you reach the 2026 IRA Limits consistently.
2. Leverage Catch-Up Contributions
If you are aged 50 or older, take full advantage of the catch-up contribution provision. This additional contribution amount can significantly boost your savings, especially if you’re playing catch-up on your retirement planning. For 2026, ensure you incorporate this extra amount into your budget if eligible.
3. Consider a Backdoor Roth IRA
For high-income earners who exceed the direct Roth IRA contribution limits, the backdoor Roth IRA strategy remains a viable option. This involves contributing non-deductible funds to a Traditional IRA and then immediately converting them to a Roth IRA. While seemingly complex, it’s a legitimate way to get money into a Roth account and enjoy tax-free withdrawals in retirement. It’s essential to understand the pro-rata rule if you have existing pre-tax IRA balances, as this can complicate the tax implications. Consulting a tax professional is highly recommended before pursuing this strategy.
4. Diversify Your Retirement Accounts
Don’t put all your eggs in one basket. While IRAs are excellent, consider diversifying your retirement savings across various account types, such as 401(k)s, 403(b)s, or even HSAs (Health Savings Accounts) if eligible. Each account offers distinct advantages. For instance, contributing enough to your 401(k) to receive the full employer match is often considered “free money” and should be a priority before maximizing IRA contributions.
5. Rebalance Your Portfolio Regularly
Regardless of the 2026 IRA Limits, periodically reviewing and rebalancing your investment portfolio is crucial. Ensure your asset allocation aligns with your risk tolerance and time horizon. As you get closer to retirement, you might shift towards a more conservative allocation to protect your accumulated wealth.
6. Stay Informed and Adjust
Financial regulations and personal circumstances change. Stay informed about future IRA limit adjustments and other relevant tax law changes. Regularly review your financial plan to ensure it remains aligned with your goals and the most current regulations. This proactive approach will help you adapt to new 2026 IRA Limits and beyond.
Impact of Inflation and Economic Factors on 2026 IRA Limits
The adjustments to the 2026 IRA Limits are not arbitrary; they are a direct response to prevailing economic conditions, primarily inflation. The IRS uses specific metrics, such as the Consumer Price Index for All Urban Consumers (CPI-U), to determine how much these limits should increase to maintain their real value over time. High inflation, as experienced in recent years, often translates to more significant increases in contribution limits to ensure that individuals can save adequately for retirement without their purchasing power being eroded.
Economic growth also plays a role. A strong economy can lead to higher wages, which in turn necessitates higher income phase-out ranges for Roth IRAs and deductibility phase-outs for Traditional IRAs. The goal is to ensure that these thresholds remain relevant to the earnings of a broad spectrum of the working population. Without these adjustments, the effectiveness of IRAs as retirement savings vehicles would diminish for many, especially those whose incomes rise with economic prosperity.
Furthermore, legislative changes, though less frequent for annual IRA limits, can also influence these figures. While the 2026 IRA Limits are primarily driven by inflation indexing, it’s always worth noting that broader retirement reform legislation could introduce more substantial changes in the future. Financial policy makers continually assess the adequacy of retirement savings vehicles and make adjustments to encourage greater participation and better outcomes for retirees.
For individuals, understanding this interplay between inflation, economic factors, and the 2026 IRA Limits is crucial. It underscores the importance of not just meeting the limits but also ensuring your investments are growing at a rate that outpaces inflation. Diversifying your portfolio and considering inflation-protected securities can be part of a robust strategy to safeguard your retirement nest egg against the erosive effects of rising prices.
Common Mistakes to Avoid with Your IRA Contributions
Even with a clear understanding of the 2026 IRA Limits, it’s easy to make common mistakes that can hinder your retirement savings. Being aware of these pitfalls can help you avoid them and ensure your contributions are optimized.
1. Not Contributing Enough (or Anything at All)
The most significant mistake is failing to contribute to an IRA or not contributing the maximum allowable amount. Even small, consistent contributions can grow substantially over decades, thanks to the power of compounding. Don’t underestimate the long-term impact of even a few hundred dollars annually.
2. Missing the Contribution Deadline
IRA contributions for a given tax year can typically be made up until the tax filing deadline of the following year (usually April 15th). Missing this deadline means you forfeit the opportunity to contribute for that specific year, losing out on valuable tax advantages and growth potential. Be mindful of the deadline for the 2026 IRA Limits.
3. Over-Contributing to Your IRA
Contributing more than the annual limit can lead to penalties from the IRS. These penalties are typically 6% of the excess contribution for each year the excess remains in the account. Carefully track your contributions to avoid exceeding the 2026 IRA Limits, especially if you have multiple IRA accounts.
4. Ignoring Income Limits for Roth IRAs
If your Modified Adjusted Gross Income (MAGI) exceeds the Roth IRA income phase-out limits, making direct contributions can lead to penalties. If you’re a high-income earner, explore the backdoor Roth IRA strategy instead, or consider a Traditional IRA. Always be aware of the income thresholds for the 2026 IRA Limits.
5. Neglecting Investment Allocation
Contributing money to an IRA is only half the battle. That money needs to be invested wisely to grow. Leaving your contributions in cash or a low-interest savings account within your IRA will severely limit its growth potential. Choose appropriate investments that align with your risk tolerance and time horizon.
6. Forgetting About Catch-Up Contributions
For those aged 50 and over, forgetting to make catch-up contributions is a missed opportunity to significantly boost retirement savings. These additional contributions can make a substantial difference in your final retirement nest egg, especially under the new 2026 IRA Limits.
By being mindful of these common mistakes, you can ensure your IRA contributions are strategic, compliant, and maximally effective for your long-term financial health.
Conclusion: Proactive Planning for Your Retirement Future
The anticipation of the 2026 IRA Limits for Roth and Traditional IRAs underscores the continuous evolution of retirement planning. These annual adjustments by the IRS are not merely bureaucratic updates; they are critical components of your financial strategy, offering opportunities to enhance your savings and secure your future. By staying informed about these changes, understanding the nuances between different account types, and employing smart contribution strategies, you can significantly impact the trajectory of your retirement wealth.
Whether you’re leveraging the tax-deductible benefits of a Traditional IRA, enjoying the tax-free withdrawals of a Roth IRA, or utilizing advanced strategies like the backdoor Roth, proactive planning is key. Remember to factor in potential catch-up contributions if you’re aged 50 or over, and always be mindful of income phase-out ranges and deductibility rules. The financial landscape is ever-changing, influenced by inflation, economic trends, and legislative decisions, making continuous education and adaptation essential.
Don’t wait for the official announcements to start thinking about your 2026 contributions. Use the projections and insights provided in this guide to begin formulating your strategy now. Consult with a qualified financial advisor to tailor these general guidelines to your specific financial situation, ensuring you maximize every opportunity presented by the 2026 IRA Limits. Your diligent efforts today will pave the way for a more secure and prosperous retirement tomorrow. Start planning, start contributing, and take control of your financial destiny.